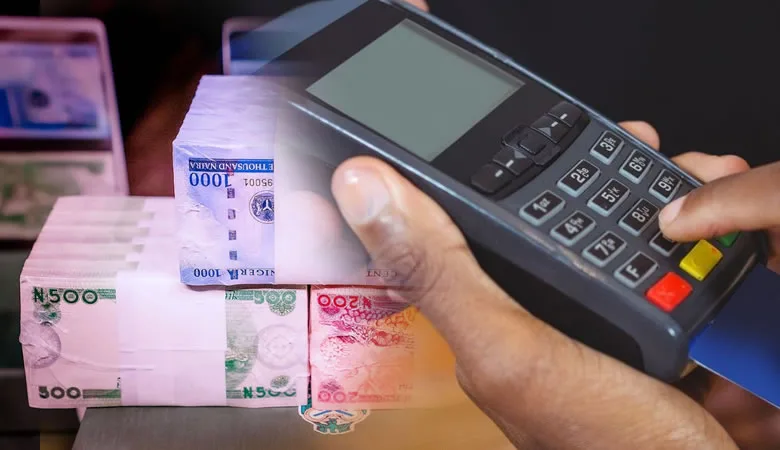
The number of Nigerian adults using digital financial services has risen sharply, with about 77 million people, representing 64.4% of the adult population, now using digital channels, according to the 2026 Access to Financial Services in Nigeria (A2F) Survey.
The latest figure represents a major increase from the 45% recorded in 2023, highlighting the growing importance of digital payments and other technology-driven financial services in Nigerians’ everyday lives. The survey was conducted by Enhancing Financial Innovation and Access (EFInA) in partnership with the National Bureau of Statistics (NBS).
But while digital finance is expanding rapidly, the report shows that access remains uneven across the country.
Digital payment adoption is significantly higher in urban areas than in rural communities, with the gap reflecting differences in infrastructure, connectivity and access to financial services.
Gender disparities are also particularly pronounced in parts of northern Nigeria. The survey found that women generally lag behind men in the use of digital financial services, with the difference much wider in the North than in southern parts of the country.
The wider financial inclusion picture, however, shows substantial progress.
EFInA reported that 79% of Nigerian adults, about 94.2 million people, now use some form of financial product or service, while formal financial inclusion has reached 73%, representing approximately 87.2 million adults. The formal inclusion figure is above the 70% target established under Nigeria’s National Financial Inclusion Strategy.
Despite the increase in access, the survey warns that having a bank account or being able to use digital financial services does not necessarily mean that households are financially secure.
EFInA said only about 31% of formally included adults are financially healthy, while 70.1% report ongoing financial or welfare stress. The organisation has therefore called for greater emphasis on whether financial services actually improve people’s ability to cope with economic shocks, rather than focusing mainly on the number of accounts opened.
Credit is another area highlighted by the survey.
Formal borrowing has increased to about 10% of adults, nearly twice the 5.3% recorded in 2023. However, the purpose of borrowing appears to be shifting towards immediate household needs and coping with financial pressure rather than business expansion.
EFInA reported that the share of formal borrowing used for coping and consumption increased to 40.8%, while the proportion used for productive business activities declined to 34.3%.
The pattern suggests that more Nigerians are turning to formal credit, but a significant share are doing so to meet urgent expenses rather than to invest in activities that could generate additional income.
The survey also points to the continued importance of informal financial channels. Nigerians still rely on informal savings and borrowing arrangements because they are often viewed as faster, simpler, closer to home and more flexible than some formal alternatives.
Cash, meanwhile, remains deeply embedded in Nigeria’s economy despite the growth of digital payments.
EFInA’s findings indicate that cash continues to be important because many Nigerians earn their income in cash, use it for small everyday transactions and keep physical money available as protection against problems such as network failures and transaction disruptions.
This reliability issue could become increasingly important as more Nigerians depend on digital financial services.
EFInA has warned that service failures can undermine customer confidence, particularly when transactions fail or refunds are delayed. The organisation has therefore recommended that policymakers and financial institutions pay greater attention to service reliability, financial health and people’s ability to withstand emergencies.
The survey also highlights the continuing gender dimension of financial inclusion. Women business owners recorded substantial progress, with formal financial inclusion rising from about 68% in 2023 to 76% in 2026, while inclusion among women farmers increased from 43% to 54%.
However, EFInA stressed that progress remains uneven, particularly for people who depend on others for income and for communities that continue to face barriers to financial services.
The findings point to a changing financial inclusion challenge for Nigeria. The issue is no longer simply getting more people into the formal financial system, but ensuring that access translates into savings, productive credit, protection from shocks and stronger household financial security.
As digital finance becomes increasingly mainstream, the report suggests that the next phase of Nigeria’s financial inclusion efforts will need to focus not only on access, but also on whether the system actually improves the financial well-being of the people using it.
Reporting by TalkNaijaMedia

Reader Comments (0)
No comments yet. Be the first to share your perspective on this report.