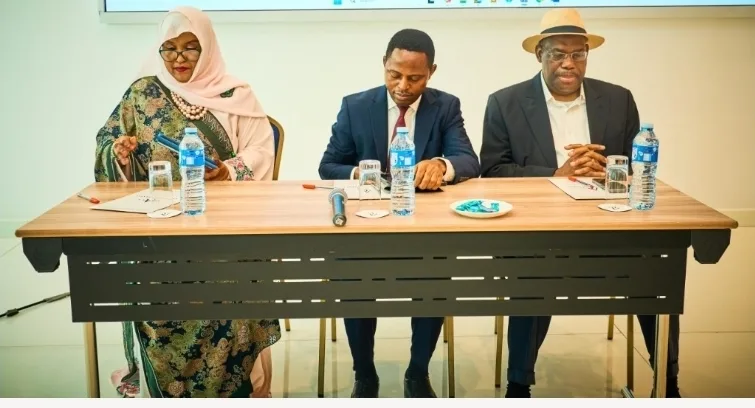
The exercise will help Nigeria assess how effectively its laws, regulatory systems and institutions are addressing money laundering, terrorism financing and the financing of the proliferation of weapons of mass destruction, collectively covered by the AML/CFT/CPF framework.
Speaking at the opening of the training, NFIU Chief Executive Officer Hafsat Abubakar Bakari said Nigeria must demonstrate that its financial crime prevention measures produce practical results, rather than simply show that the necessary laws and institutions exist.
Bakari described the programme as part of the country’s continuing efforts to strengthen its financial system following its removal from the Financial Action Task Force (FATF) grey list in October 2025.
She stressed that the forthcoming assessment would require credible evidence of implementation, effective coordination among relevant agencies and measurable progress in detecting and disrupting financial crimes.
GIABA Director-General Mam Cherno Jallow, represented at the programme by the organisation’s Director of Evaluations and Compliance, Giwa Siman Sechap, also underscored the importance of a shared understanding of the international assessment methodology.
Sechap said mutual evaluation was a collective national responsibility that required institutions to demonstrate tangible outcomes beyond technical compliance with international standards.
He explained that the training would improve participants’ knowledge, coordination and ability to provide assessors with accurate information supported by verifiable evidence.
SecFIN Africa Country Representative Professor Shehu Abdullahi called for sustained investment in institutional capacity and stronger cooperation among government agencies.
According to him, effective preparation depends on institutions sharing reliable information, working towards common objectives and taking collective responsibility for national priorities.
He added that the programme would help Nigeria identify outstanding weaknesses, consolidate existing progress and demonstrate the effectiveness of its financial integrity framework.
Government Agencies Join Forces
The training has brought together representatives from government institutions responsible for financial intelligence, regulation, law enforcement, prosecution, revenue collection, border control and national security.
Participating organisations include the Central Bank of Nigeria, Economic and Financial Crimes Commission, Federal Ministry of Justice, Independent Corrupt Practices and Other Related Offences Commission, Department of State Services, Defence Intelligence Agency and Nigeria Police Force.
Others include the Corporate Affairs Commission, Bureau of Public Procurement, Code of Conduct Bureau, National Drug Law Enforcement Agency, National Agency for the Prohibition of Trafficking in Persons, National Counter Terrorism Centre, Nigeria Customs Service, Nigeria Revenue Service and Nigeria Security and Civil Defence Corps.
Regulatory and sector-specific institutions represented include the National Insurance Commission, Securities and Exchange Commission, Mining Cadastral Office, Nigeria Extractive Industries Transparency Initiative, Nigeria Export Processing Zones Authority and Oil and Gas Free Zones Authority, alongside other relevant agencies.
Their combined responsibilities cover the reporting and analysis of suspicious financial transactions, investigations and prosecutions, asset recovery, beneficial ownership transparency, regulatory supervision and enforcement of financial controls.
The NFIU said cooperation among these institutions would be essential to demonstrating that Nigeria’s anti-money laundering and counter-terrorism financing framework is effective in practice.
Training to Cover Digital Finance and Asset Recovery
The programme will address several areas relevant to the assessment, including financial intelligence, regulatory supervision, virtual assets, beneficial ownership, criminal investigations and prosecutions.
Other subjects include asset confiscation, international cooperation, targeted financial sanctions and the risks associated with the financing of proliferation.
Participants will also take part in practical exercises and simulated assessment interviews. These sessions are intended to prepare officials to explain their institutions’ responsibilities, provide reliable data and present evidence of actions taken to address financial crime risks.
The focus on implementation reflects the growing importance of demonstrating outcomes in areas such as financial intelligence sharing, investigations, prosecutions, international cooperation and the recovery of criminal proceeds.
The NFIU disclosed that Nigeria had expanded its pool of globally accredited experts in FATF standards from fewer than 10 to 25 over the preceding two years.
It also indicated that the capacity-building initiative could be expanded through additional training groups of between 100 and 150 participants every quarter, with a possible extension to relevant private-sector stakeholders in the future.
Nigeria Builds on Grey List Exit
The latest training follows a national stocktake and gap analysis coordinated by the NFIU through the Inter-Ministerial Committee, with support from agencies including the EFCC, DSS, ICPC, CBN, NAICOM and SEC.
The exercise is intended to review how existing measures are being implemented, identify areas of progress and determine where further action is needed to strengthen the country’s financial crime prevention system.
Nigeria was removed from the FATF list of jurisdictions under increased monitoring, commonly known as the grey list, in October 2025 after the international body acknowledged progress in addressing identified weaknesses in the country’s anti-money laundering and counter-terrorism financing framework.
However, removal from the list does not end the need for continued reforms or effective enforcement. The country must maintain progress and demonstrate that its systems can respond to emerging risks.
The next mutual evaluation is therefore an important test of whether the institutional improvements made in recent years are translating into sustained results.
Bakari said the ultimate objective was to turn cooperation among government institutions into measurable improvements in the detection and disruption of financial crimes.
The NFIU maintained that the initiative reflects Nigeria’s commitment to stronger inter-agency collaboration, improved technical expertise and evidence-based enforcement as preparations continue for the next international assessment.
Reporting by TalkNaijaMedia
Reader Comments (0)
No comments yet. Be the first to share your perspective on this report.